If you have credit card balances and you're thinking about buying a home, you may be wondering:“Do I need to pay off all my credit cards before I can buy a house?”The answer may surprise
Can You Buy a House in Georgia With Credit Card Debt? [2026 Guide]
Dated: September 1 2026
Views: 6
If you have credit card balances and you're thinking about buying a home, you may be wondering:
“Do I need to pay off all my credit cards before I can buy a house?”
The answer may surprise you.
You do not necessarily need to be debt-free to become a homeowner.
Many people purchase homes while carrying credit card balances, student loans, car payments, and other debts. What matters is how those monthly obligations affect your overall financial profile and mortgage qualification.
If buying a home in Georgia is one of your goals, don't automatically count yourself out because you have credit card debt.
Here's what you need to know.
Can You Get a Mortgage With Credit Card Debt?
Potentially, yes.
Having credit card debt does not automatically prevent you from qualifying for a mortgage.
Mortgage lenders look at your entire financial picture, which may include:
- Income
- Employment history
- Credit profile
- Monthly credit card payments
- Car payments
- Student loans
- Personal loans
- Other recurring debts
- Down payment
- Available funds
- Proposed housing payment
- Loan program
Your total credit card balances matter, but lenders are also concerned with the required monthly payments associated with those accounts.
This is where your debt-to-income ratio becomes important.
What Is Debt-to-Income Ratio?
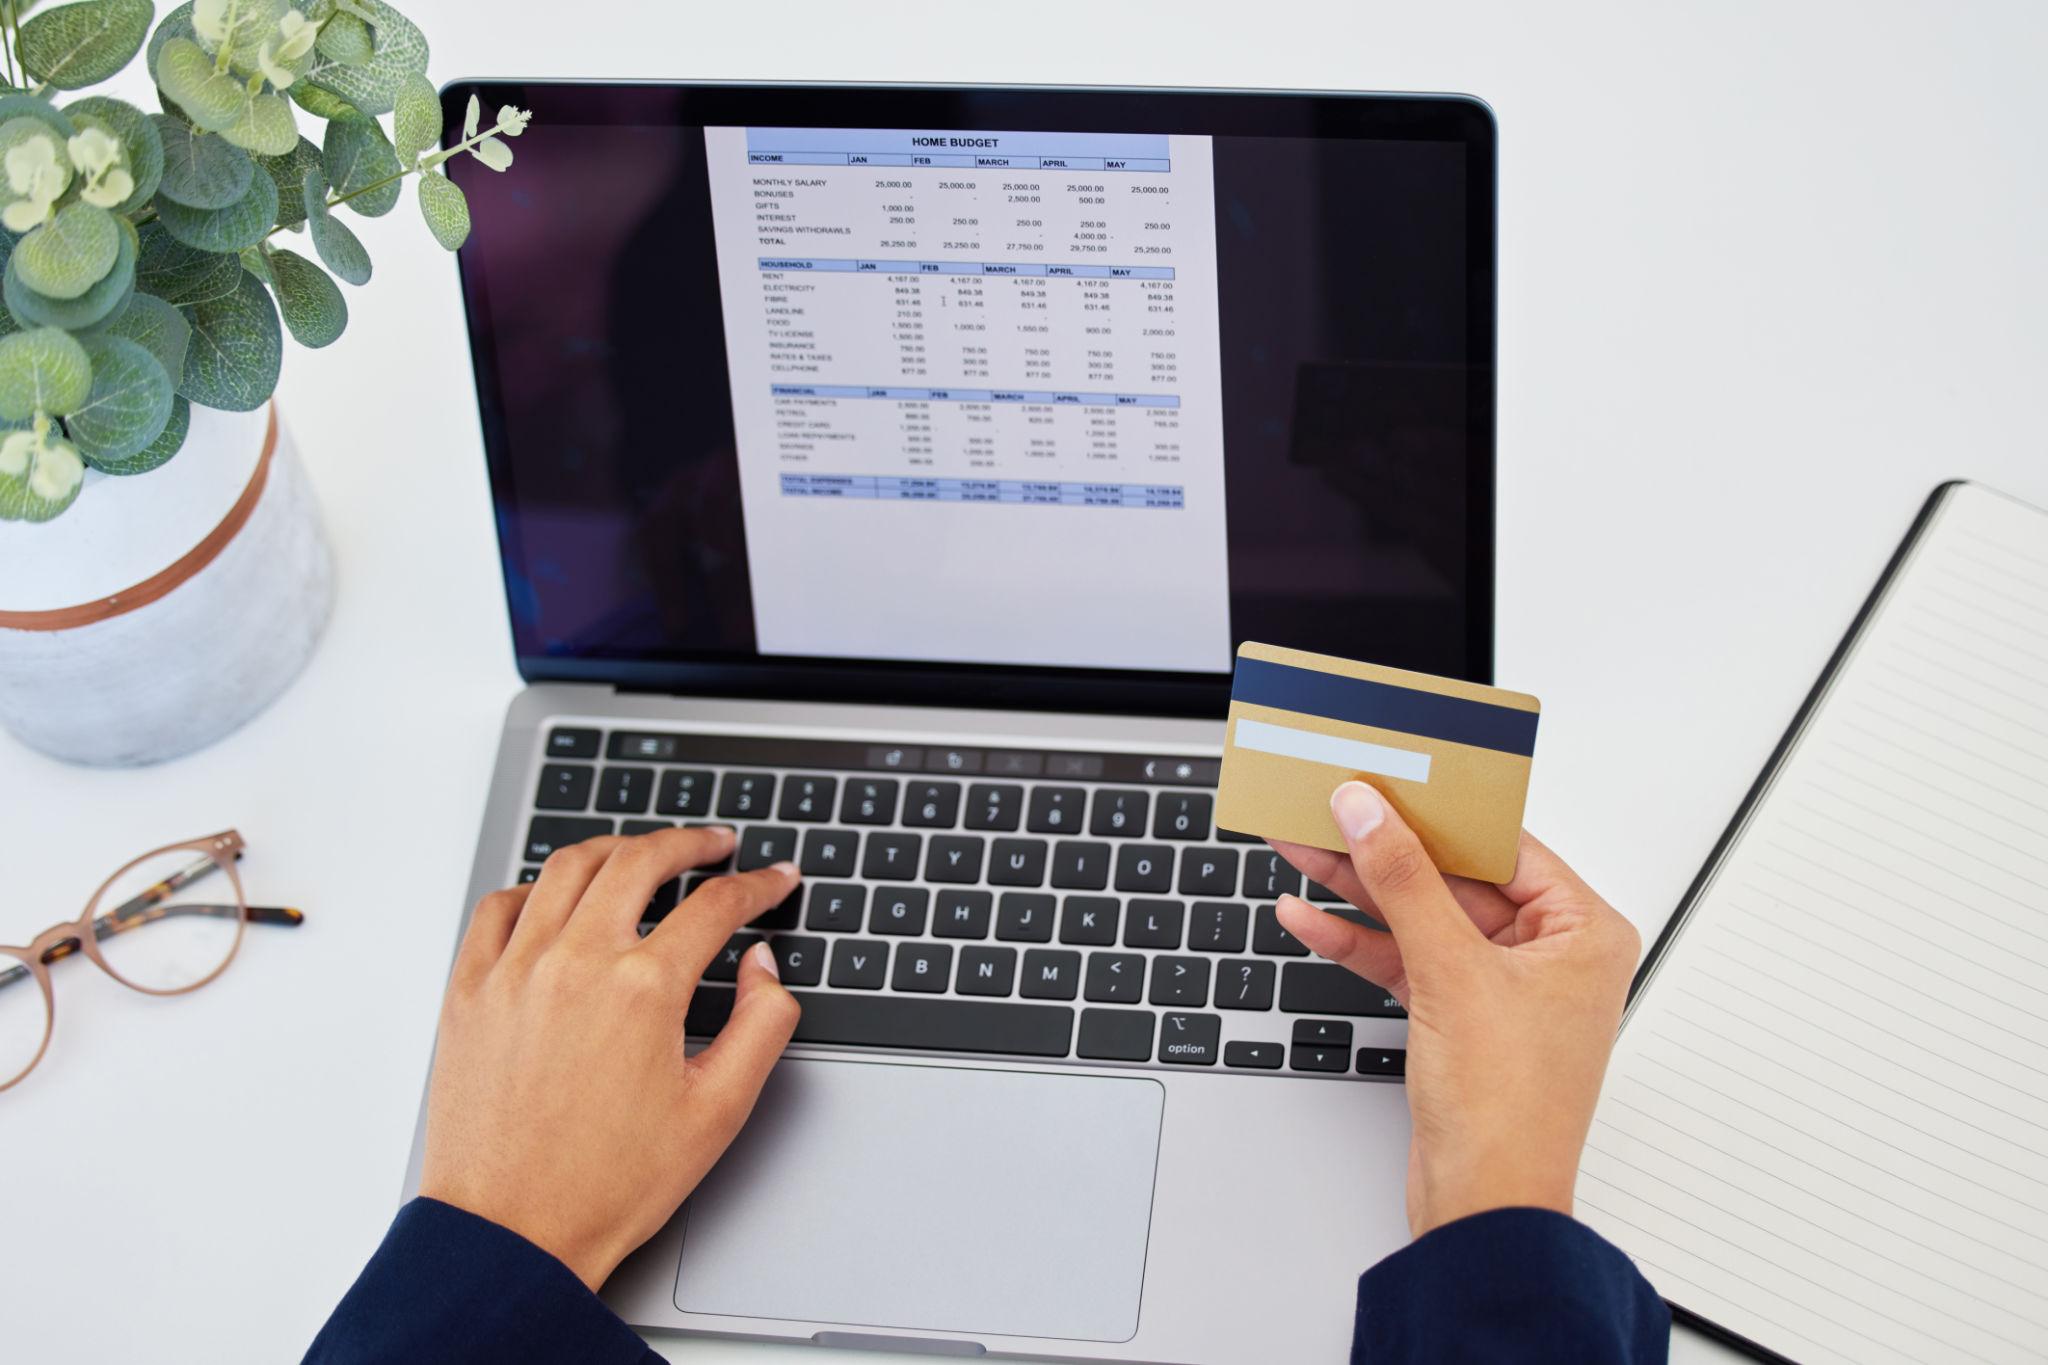
Your debt-to-income ratio, commonly called DTI, compares qualifying monthly debt obligations with your gross monthly income.
For example, lenders may consider monthly obligations such as:
- Credit card minimum payments
- Auto loans
- Student loans
- Personal loans
- Existing mortgages
- Certain other recurring debts
Your proposed housing payment is also factored into the equation.
Generally, the more monthly debt you carry relative to your income, the less room you may have for a mortgage payment.
But that doesn't necessarily mean you can't buy.
It may simply affect how much house you can afford.
Does Credit Card Debt Reduce How Much House You Can Afford?
It can.
Let's look at a simple example.
Imagine two buyers have the same income.
Buyer A has $150 per month in required credit card payments.
Buyer B has $800 per month in required credit card payments.
Everything else being equal, Buyer A may have more room within their debt-to-income ratio for a housing payment.
This is why two buyers making the same salary can potentially qualify for very different home prices.
Your salary matters.
But your monthly obligations matter too.
Related: How Much House Can I Afford in Georgia? [2026 Guide]
How Much Credit Card Debt Is Too Much to Buy a House?
There isn't one dollar amount that automatically means you have “too much” credit card debt to purchase a home.
For example, having $10,000 in credit card debt doesn't tell us enough by itself.
We also need to know:
- What are your required monthly payments?
- What is your income?
- What other debts do you have?
- What does your credit profile look like?
- How much are you planning to put down?
- What price range are you considering?
- Which mortgage program are you using?
A buyer with $15,000 in credit card debt and strong income could potentially be in a better mortgage position than someone with $5,000 in credit card debt and considerably less income.
Context matters.
Does Credit Card Utilization Affect Buying a House?
Credit card debt can affect more than your debt-to-income ratio.
It can also affect your credit utilization, which is one factor that can influence your credit profile.
Credit utilization generally refers to how much of your available revolving credit you're using.
For example, if you have a credit card with a $10,000 limit and a $9,000 balance, you're using a large percentage of the available credit on that account.
Reducing revolving balances may potentially help your overall credit profile, depending on your circumstances.
But this is where strategy becomes especially important.
Don't start making major financial moves simply because you're preparing to buy a house.
Have a mortgage professional evaluate your situation first.
Should You Pay Off Credit Cards Before Applying for a Mortgage?
Maybe—but don't assume paying everything off is automatically the best strategy.
Let's say you've saved $15,000 toward buying a home.
You could potentially use that money for:
- Paying down credit card debt
- Your down payment
- Closing expenses
- Financial reserves
- Moving expenses
- A combination of several things
Which option makes the most sense depends on your individual financial profile.
A lender may determine that paying down a particular credit card could improve your qualification.
Or you may discover that preserving some of your available cash is more important.
This is why I recommend talking with a lender before making large payments or moving significant amounts of money.
Which Credit Card Should You Pay Down First Before Buying a House?
Don't automatically assume the card with the largest balance should be your first priority.
If your goal is preparing for mortgage qualification, your lender can help you evaluate factors such as:
- Required monthly payment
- Current balance
- Credit limit
- Credit utilization
- Available cash
- Overall debt-to-income ratio
The strategy that saves you the most interest and the strategy that has the greatest immediate effect on mortgage qualification may not always be identical.
That's why individualized guidance matters.
Don't guess. Know your numbers first.
Should You Close Credit Cards After Paying Them Off?
Be careful.
Paying off a credit card and closing a credit card are two different actions.
Closing an account can potentially affect factors within your credit profile, including the amount of available revolving credit you have.
If you're preparing for a mortgage, avoid making unnecessary changes to your credit profile without first discussing them with your lender.
That includes:
- Closing credit cards
- Opening new cards
- Financing furniture
- Buying a vehicle
- Co-signing for someone
- Taking out personal loans
- Making other major credit changes
Once you've started the mortgage process, keeping your financial situation stable can be especially important.
Can You Buy a $400K House With Credit Card Debt?
Potentially.
Credit card debt doesn't create a specific maximum home price.
A buyer could have credit card balances and still potentially qualify for a $400,000 home depending on their income, monthly obligations, credit profile, down payment, interest rate, loan program, taxes, insurance, and other factors.
Instead of asking:
“Can I buy a $400K house if I have credit card debt?”
Ask:
“Based on my income and all of my monthly obligations, what purchase price and monthly payment make sense for me?”
That's a much more useful question.
Related: How Much Income Do You Need to Buy a $400K House in Georgia?
What If I Have Credit Cards AND Student Loans?
You're not alone.
Many prospective buyers are balancing multiple types of debt.
You could potentially have:
- Student loans
- Credit cards
- A car payment
and still qualify to purchase a home.
Again, the existence of debt isn't necessarily the deciding factor.
The lender needs to evaluate how your monthly obligations compare with your qualifying income and the requirements of your mortgage program.
Related: Can You Buy a House in Georgia With Student Loan Debt? [2026 Guide]
Can Paying Down Credit Cards Increase Your Homebuying Power?
Potentially.
If credit card payments are contributing significantly to your debt-to-income ratio, reducing certain obligations could potentially improve your purchasing power.
Paying down revolving balances could also potentially affect your credit profile.
But don't assume that putting every available dollar toward your cards is the right solution.
The goal is to determine which actions provide the greatest benefit for your particular situation.
This is where starting early can make a big difference.
What If My Credit Card Debt Is Keeping Me From Qualifying?
If you're not able to qualify for the home price you want today, don't immediately give up.
Find out why.
Maybe you need to:
- Reduce certain credit card balances
- Lower your monthly debt obligations
- Improve your credit profile
- Increase your savings
- Adjust your initial price range
- Allow additional time to prepare
Once you know what's holding you back, you can create a plan around it.
Sometimes the difference between being unable to purchase and becoming mortgage-ready is simply having enough time and the right strategy.
How Far in Advance Should You Prepare to Buy a House?
If you're considering purchasing within the next 6–12 months, you don't have to wait until you're ready to start touring houses to reach out.
Starting early gives you time to:
- Understand your credit
- Review your debt
- Determine your purchasing power
- Build your savings
- Explore loan options
- Address potential obstacles
- Create a realistic timeline
And if you're already ready?
Great. We can move forward from there.
The point is that you don't need to figure out whether you're ready on your own.
Stop Waiting Until Your Finances Are “Perfect”
This is one of the biggest misconceptions I hear from future homeowners:
“I'm going to wait until I pay everything off before I talk to a Realtor or lender.”
But how do you know that's actually what you need to do?
You could spend a year paying down the wrong debt.
You could use savings that would have been valuable during your home purchase.
Or you could discover that you were closer to qualifying than you thought.
You don't need perfect finances to start asking questions.
You need accurate information and a plan.
Thinking About Buying a Home in Georgia?
At The Turner Collective Real Estate Group, we believe your homebuying journey can begin long before you're ready to receive the keys.
Our concierge approach is about making the process easier by helping connect you with the right professionals and resources from start to finish.
If credit card debt or credit concerns are making you hesitate, we can help connect you with trusted resources for:
- Credit improvement
- Mortgage financing
- Down-payment assistance resources
- Home searches
- New construction
- Inspections
- Insurance
- Closing services
- Renovations and home improvements
Don't disqualify yourself before you've even explored your options.
Let's find out where you are, determine where you want to go, and create a plan to help you get there.
Guiding You Home — With Purpose and Passion.
You don't need perfect finances to start. Let's help you understand where you stand and what your next step should be.
Continue Your Homebuying Research
Read these next:
- How Much House Can I Afford in Georgia? [2026 Guide]
- How Much Income Do You Need to Buy a $400K House in Georgia?
- Can You Buy a House in Georgia With Student Loan Debt? [2026 Guide]
- What Credit Score Do You Need to Buy a House in Georgia? [2026 Guide]
- How Much Money Do You Need to Buy a House in Georgia?
- First-Time Buyer FAQ Cheat Sheet
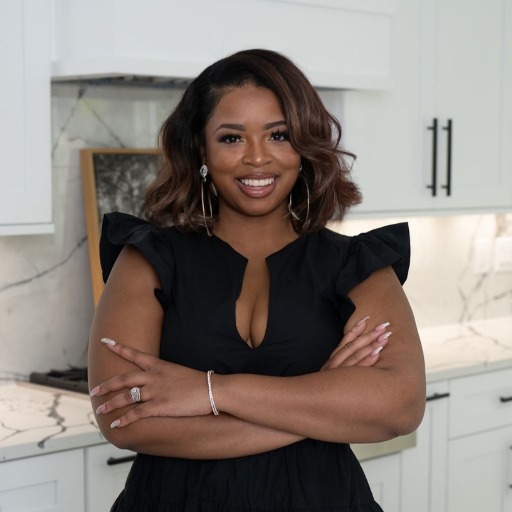
Angel Turner
Angel Turner is a Top 10% Producing REALTOR® and Team Lead of The Turner Collective Real Estate Group at Watch Realty Co – Gwinnett. As a Real Estate Negotiation Expert (RENE) and former edu....
Latest Blog Posts
One of the first questions future homeowners ask is:"How much house can I actually afford?"If you're thinking about buying a home in Georgia, the answer isn't based on your salary alone. Your income
If you're shopping for a home in Georgia, you may be wondering:“How much do I need to make to afford a $400,000 house?”The answer isn't as simple as choosing one salary.While your income
If you have student loans and you're thinking about buying a home, you may be asking:“Do I need to pay off my student loans before I can buy a house?”For many Georgia homebuyers, the
 ©2026 Georgia Multiple Listing Service All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may
 Listings identified with the FMLS IDX logo come from FMLS and are held by brokerage firms other than the owner of this website. The listing brokerage is identified in any listing details. Information is deemed reliable but is not guaranteed. If you believe any FMLS listing contains material that infringes your copyrighted work please
